

What is a brokerage account?
What is a brokerage account?
Brokerage accounts are investment accounts for buying and selling securities, like stocks, bonds, and ETFs. Explore how they work, including taxes and fees
What is a brokerage account?
Brokerage accounts are investment accounts for buying and selling securities, like stocks, bonds, and ETFs. Explore how they work, including taxes and fees
11.04.2026
Key takeaways
- A brokerage account lets you buy, sell, and hold stocks, bonds, mutual funds, and ETFs through a brokerage firm as you pursue financial goals.
- Taxable brokerage accounts have flexible withdrawal rules and no annual contribution limits, but realized gains, dividends, and interest may be taxable.
- Brokerage accounts may be self-directed or managed. When comparing firms, consider investment choices, fees, account minimums, and risk.
Investing for specific money goals is a top priority for more than 4 in 5 Americans (86%), and taxable brokerage accounts are a common part of an investment strategy.
Brokerage accounts allow you to buy and sell investments, incorporate portfolio guidance, and withdraw funds as you reach your financial goals. Unlike retirement accounts, they have no income limits, early withdrawal penalties, or contribution limits
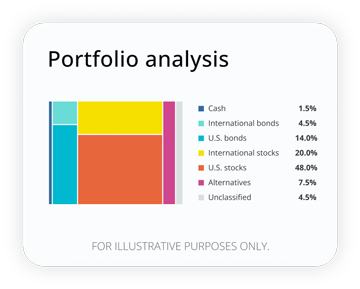
How well are your investments performing?
Analyze your portfolio in minutes and receive a target allocation for your goals.
What is a brokerage account?
A brokerage account is an investment account for buying and selling securities through a financial institution.
There are many different platforms that enable opening a brokerage account, and the investments you’ll have access to depend on the platform you choose. Many brokerage accounts allow you to trade individual stocks and bonds, as well as pooled assets like mutual funds and exchange-traded funds (ETFs).
Keep in mind that a self-directed brokerage account is intended for knowledgeable investors who understand the risks associated with the account.
How do brokerage accounts work?
When you place funds in a brokerage account, you can use this money to buy and sell securities — all of which remain in the account. You can typically connect it to your bank account and transfer funds into it. With the money in your brokerage account, you can then purchase stocks, bonds, mutual funds, and other investments. As you sell these securities, the proceeds generally return to your account as cash, and any realized gains may be subject to taxes.
When it comes to managing your investments, you have several options:
- Self-directed brokerage accounts (SDBAs): allow you to manage your own investments. This gives you the flexibility to build your own portfolio of stocks, bonds, or diversified investments like mutual funds and ETFs. You can open an SDBA with most major brokerage firms.
- Managed brokerage accounts are overseen by an advisor or advisory firm that manages your investments for you. Investment managers get to know your financial goals, risk tolerance, and time horizon and will choose an asset allocation that’s appropriate for you. In exchange for them managing your portfolio, investment managers generally charge an advisory fee for their services.
- “Robo-advisor” brokerage accounts are managed by a computer algorithm. Your advisory firm’s algorithm will select investments based on your financial goals and preferences.
Types of brokerage accounts: Cash accounts and margin accounts
When you open a taxable brokerage account, you can choose between a cash account and a margin account:1
- Cash accounts: Allow you to buy securities with money you transfer into your account. If you have $1,000 in cash in your brokerage account, you can buy up to $1,000 in securities. These are the most common types of brokerage accounts.
- Margin accounts: Allow you to borrow money from your brokerage firm to buy securities, though you will pay interest on the amount lent to you. You’re still responsible for providing a percentage of the funds, and the securities themselves serve as the collateral for the loan. You may need to deposit additional funds when collateral values decline.
Potential benefits and drawbacks of brokerage accounts
A brokerage account can be a powerful tool to help you grow wealth and save for financial goals.
They offer several key benefits, including:
- Potential for higher returns: Investments made in a brokerage account may have a greater potential for investment growth than funds kept in a savings accounts. Be aware that certain investments available in a brokerage account can have more risk of loss than savings accounts.
- Diversified investment options: Brokerage accounts offer a wide range of investments options. You can build a diversified portfolio of stocks, bonds, mutual funds, and ETFs.
- Flexibility in trading: Brokerage accounts can offer a level of investment flexibility that may not be available in employer sponsored retirement plans and college savings accounts. You’re generally free to buy securities to hold for many years, actively trade stocks day to day, or something in between based on market conditions and their personal strategies.
- SIPC-insured: Assets held at SIPC-member brokerage firms may qualify for protection if the brokerage fails and your assets go missing. SIPC protection generally covers up to $500,000, including a $250,000 limit for cash. However, SIPC doesn't protect against investment losses due to market performance.2
Brokerage accounts can come with drawbacks, including:
- No guarantee on earnings: Most investments available in brokerage accounts do not guarantee returns on your investments. However, stock market returns overall have averaged about 10% annually for nearly the last century, as measured by the S&P 500® index.3
- Fees: There are often costs involved with trading, portfolio management, and specific investments. These can add up over time, though passive investing often involves lower overall cost than active trading.
How to open a brokerage account
Opening a brokerage account can normally be done in a few steps:
- Choose your account type: Decide whether you’d prefer to manage your own investments or hire a professional or service to do so.
- Select a brokerage firm: Research your options and compare investment options and services, fees, and account minimums.
- Sign up for an account: Fill out all forms necessary to open your new account. Brokerage firms may request basic information, including your name and social security number, as well as any information regarding additional investment services.
- Fund the account: Transfer money to your new account, keeping in mind any investment minimums. Often, you can connect your bank account to your brokerage account to easily transfer funds between them.
- Invest your funds: Begin investing your funds in a diverse set of securities based on your financial goals and risk tolerance. Consider working with an investment manager or utilizing robo-advisor services until you feel comfortable doing so on your own.
- Manage your investments: If managing your own account, consider periodically reviewing your investment performance. Ongoing portfolio management can help ensure that your investments continue to align with your goals and risk tolerance while accounting for major market fluctuations.
Read more: How to start investing: A beginner’s guide to investment basics
Taxable brokerage accounts vs. retirement accounts
Brokerage accounts and retirement accounts, including individual retirement accounts (IRAs) and 401(k) plans, are investment accounts where you can buy and sell securities. However, these accounts differ when it comes to their tax implications, contribution and withdrawal rules, and primary uses.
| Taxable brokerage account | IRA | 401(k) |
Eligibility | Generally available to anyone | Generally available to anyone with taxable income; Roth IRAs have additional income caps | Generally only available through an employer |
Investment options | Greatest flexibility, with additional trading features | Flexible, determined by the investment firm or provider | Varies between employers |
Taxes | Capital gains and earnings are tax | Traditional IRAs may offer upfront tax break; Roth IRAs offer tax-free qualified withdrawals in retirement | Same as IRA, with taxes advantages depending on Roth vs. traditional arrangement |
Withdrawals restrictions | No | Withdrawals may be subject to an early withdrawal penalty | |
Contribution limits | No | ||
Employer matching | No | No | |
Primary use | General investing and wealth building | Tax-advantaged retirement investing outside of a workplace plan | Tax-advantaged retirement investing with employer matching |
Read more: IRA vs 401(k): Key differences
Taxation of brokerage accounts
Investments held in a taxable brokerage account can generate taxable income through:
- Short-term and long-term capital gains
- Dividends
- Interest from CDs and bonds
There are different forms you’ll have to file with your income tax return depending on the type of investment income you have.
Tax-loss harvesting is one investment strategy that can help reduce your taxable investment income by offsetting your capital gains with losses. When you sell any asset for a capital gain, you sell another asset for a loss, thus canceling out some or all your taxable gain.
Read more: How do investing decisions affect taxes?
Is a brokerage account right for me?
Whether a brokerage account is right for you depends on your other investment accounts and your financial goals. In general, financial professionals recommend prioritizing your retirement savings over other investments. Once you’re contributing enough to your various retirement accounts to meet your long-term goals, including taking advantage of any employer matching, you might consider opening a taxable brokerage account, too.
FAQ
Can I open a brokerage account for my kids?
Yes, a custodial account is a brokerage account that an adult (usually a parent or another family member) can open on behalf of a child. The custodian is responsible for managing the investments until the child reaches adulthood.
Popular custodial accounts include:
While a custodian manages the account, anything transferred into it is the legal property of the minor. So, if you contribute money to your child’s custodial account, you can’t take it back. Once the child reaches the age of majority, which varies by state and account type, they’ll get full control of the custodial account and can use the money for anything they want.
Read more: Investing for kids: Account options and how to start
Do brokerage accounts offer potential tax advantages?
Brokerage accounts do not typically offer tax advantages as IRAs and other retirements accounts do. Instead, you’ll pay taxes annually on investment income and capital gains, even if these funds are not withdrawn from the account.
Can a brokerage account be jointly owned?
When you open a brokerage account, you can choose between either an individual or a joint account. An individual account has just one owner. A joint account, on the other hand, is co-owned by two more individuals, typically spouses.
Joint brokerage accounts can take a few different forms, including Joint Tenants with Rights for Survivorship and Tenants in Common. The key difference between these accounts is what happens if one owner dies.
In the case of Joint Tenants with Rights of Survivorship, both owners have equal ownership of the account. If one account-holder dies, the other solely owns the account. In the case of Tenants in Common, each owner owns half of the account, and if one owner dies, their share goes to the person designated in their estate plan.4
1 Investor.gov, “Types of Brokerage Accounts,” accessed November 2026.
2 SIPC, “The Securities Investor Protection Corporation (SIPC) protects customers if their brokerage firm fails,” accessed November 2026.
3 Investopedia, “S&P 500 Average Return and Historical Performance,” May 2026.
4 Investopedia, “Joint Brokerage Accounts: What You Need to Know” September 2026.
RO6076269-1126
The S&P 500 Index is a registered trademark of Standard & Poor’s Financial Services LLC. It is an unmanaged index considered indicative of the domestic large-cap equity market and is used as a proxy for the stock market in general.
Options trading may increase the risk of principal loss and is not suitable for all investors. Prior to buying or selling an option, investors should read a copy of the Characteristics & Risks of Standardized Options, also known as the options disclosure document (ODD).
ETFs are a type of exchange-traded investment product that must register as either an open-end investment company (generally known as “funds”) or a unit investment trust. ETFs are not mutual funds.
Unlike mutual funds, individual shares of ETFs are not redeemable directly with the issuer. ETF shares are a collection of securities bought and sold at market price, which may be higher or lower than the net asset value. Investment returns will vary based on market conditions and volatility, so an investor's shares, when redeemed or sold, may be worth more or less than their original cost. ETFs are subject to risks like those of their underlying securities.
Roth withdrawals are federally tax-free if they are qualified distributions as defined by the IRS. State and local taxes may apply. For a distribution to be qualified, the account must have been open for at least five years, and the withdrawal must occur after age 59½, death, or disability. Earnings withdrawn before those conditions are met may be subject to taxes and penalties. Tax laws are subject to change. State and local taxes may still apply.
 Get The Currency newsletter

Alex Graesser, CFP®, ChFC®
Contributor
Alex Graesser is a Senior Financial Professional at Empower. A Certified Financial Planner (CFP®) professional and Chartered Financial Consultant (ChFC®), he is responsible for developing enduring relationships with his clients by providing expert guidance for a lifetime of financial security.
The content contained in this blog post is intended for general informational purposes only and is not meant to constitute legal, tax, accounting or investment advice. You should consult a qualified legal or tax professional regarding your specific situation. No part of this blog, nor the links contained therein is a solicitation or offer to sell securities. Compensation for freelance contributions not to exceed $1,250. Third-party data is obtained from sources believed to be reliable; however, Empower cannot guarantee the accuracy, timeliness, completeness or fitness of this data for any particular purpose. Third-party links are provided solely as a convenience and do not imply an affiliation, endorsement or approval by Empower of the contents on such third-party websites. This article is based on current events, research, and developments at the time of publication, which may change over time.
Certain sections of this blog may contain forward-looking statements that are based on our reasonable expectations, estimates, projections and assumptions. Past performance is not a guarantee of future return, nor is it indicative of future performance. Investing involves risk. The value of your investment will fluctuate and you may lose money.
Certified Financial Planner Board of Standards Inc. (CFP Board) owns the certification marks CFP®, CERTIFIED FINANCIAL PLANNER™, CFP® (with plaque design), and CFP® (with flame design) in the U.S., which it authorizes use of by individuals who successfully complete CFP Board's initial and ongoing certification requirements.